2026 Tax Code Changes: Maximize Deductions & Credits by April 15th
Anúncios
The Latest Tax Code Changes for 2026: How to Maximize Your Deductions and Credits by April 15th
Anúncios
As the tax year 2026 approaches its inevitable conclusion, taxpayers across the nation are bracing for the annual ritual of filing their returns. However, this isn’t just another year; 2026 brings with it a fresh set of tax code changes that could significantly impact your financial obligations and opportunities. Understanding these changes is not merely a bureaucratic necessity but a strategic advantage that can help you maximize your 2026 tax deductions and credits, ultimately reducing your tax liability. The deadline of April 15th looms large, and proactive planning is your best defense against unexpected tax burdens and your best offense for securing every possible saving.
The landscape of taxation is dynamic, constantly evolving with new legislation, interpretations, and economic considerations. For 2026, several key areas have seen modifications that demand your attention. From adjustments to standard deductions and personal exemptions to changes in eligibility for various tax credits and the introduction of new provisions, a thorough review is paramount. This comprehensive guide aims to demystify these changes, providing you with actionable insights and strategies to navigate the complexities of the 2026 tax season. Our goal is to empower you to approach April 15th with confidence, knowing you’ve optimized your tax position.
We will delve into the specifics of what’s new, what’s been adjusted, and how these alterations can be leveraged to your benefit. Whether you’re an individual taxpayer, a small business owner, or someone planning for retirement, the information contained within this article will be invaluable. We’ll explore strategies for maximizing your 2026 tax deductions, identifying eligible credits, and ensuring your financial records are in impeccable order. The journey to a favorable tax outcome begins now, with informed preparation and strategic execution.
Anúncios
Understanding the Major Tax Code Adjustments for 2026
The year 2026 is poised to introduce a series of significant adjustments to the tax code, stemming from various legislative actions and economic factors such as inflation adjustments. These changes are not minor tweaks but substantial shifts that could alter how individuals and businesses calculate their taxable income and ultimately, their tax bill. Grasping the nuances of these adjustments is the first step toward effective tax planning and maximizing your 2026 tax deductions.
Inflation Adjustments and Their Impact
One of the most consistent drivers of tax code changes is inflation. The Internal Revenue Service (IRS) typically adjusts many tax provisions annually to account for inflation, preventing taxpayers from being pushed into higher tax brackets or losing the real value of deductions and credits due to rising prices. For 2026, expect to see updated figures for:
- Standard Deduction Amounts: The standard deduction is a fixed dollar amount that taxpayers can subtract from their adjusted gross income (AGI) if they choose not to itemize. Increased standard deductions mean more taxpayers might find it advantageous to take the standard deduction rather than itemizing, simplifying their tax preparation while still reducing taxable income. Keeping an eye on these updated figures is crucial for determining the most beneficial filing strategy.
- Tax Bracket Thresholds: The income ranges for each tax bracket are also adjusted for inflation. This means that more of your income might fall into lower tax brackets, or you might avoid being pushed into a higher bracket even if your income increases. Understanding these new thresholds is vital for projecting your tax liability and planning any income-related strategies.
- Qualified Business Income (QBI) Deduction Limits: For eligible self-employed individuals and small business owners, the QBI deduction allows them to deduct up to 20% of their qualified business income. The income thresholds for this deduction are also subject to inflation adjustments, which can impact who qualifies for the full deduction and at what income levels.
Key Legislative Changes Affecting Deductions and Credits
Beyond inflation, specific legislative changes can introduce new deductions, modify existing ones, or sunset certain provisions. While the exact legislative landscape can shift, potential areas of focus for 2026 include:
- Child Tax Credit Enhancements: There’s ongoing discussion and potential for further enhancements to the Child Tax Credit. These enhancements could involve increasing the maximum credit amount, making more of it refundable, or expanding eligibility. Families with children should closely monitor these developments as they could significantly impact their tax refunds or liabilities.
- Education Credits Modifications: Education-related deductions and credits, such as the American Opportunity Tax Credit and the Lifetime Learning Credit, are frequently reviewed. Changes could include updated income limitations, modified eligible expenses, or even entirely new provisions aimed at making higher education more affordable.
- Energy-Efficient Home Improvement Credits: With a growing emphasis on environmental sustainability, credits for energy-efficient home improvements are often expanded or modified. If you’re planning renovations, understanding the 2026 provisions for these credits could lead to substantial savings. This is a prime example of how everyday decisions can directly translate into maximizing your 2026 tax deductions and credits.
- Retirement Savings Incentives: Lawmakers often look for ways to encourage retirement savings. This could mean increased contribution limits for IRAs and 401(k)s, or new tax incentives for specific retirement savings vehicles. Planning your retirement contributions strategically can offer dual benefits: securing your future and reducing your current taxable income.
These adjustments underscore the importance of staying informed. What worked for your taxes in 2025 might not be the most optimal strategy for 2026. A proactive approach involves not only understanding these changes but also evaluating how they specifically apply to your financial situation. Consulting tax publications, reliable financial news sources, and potentially a tax professional can provide clarity and ensure you’re not leaving any money on the table.
Maximizing Your Deductions: A Strategic Approach for 2026
To effectively reduce your taxable income, it’s essential to understand the various avenues available for deductions. For 2026, strategic planning around these deductions can significantly lower your tax bill. This section will guide you through common and often overlooked deductions, emphasizing how to leverage them to maximize your 2026 tax deductions.
Standard vs. Itemized Deductions: Which is Right for You?
The first critical decision in tax preparation is choosing between the standard deduction and itemizing your deductions. As mentioned, the standard deduction amounts are likely to increase for 2026 due to inflation. For many taxpayers, especially those with simpler financial situations, the standard deduction offers a straightforward way to reduce taxable income without the need for extensive record-keeping.
However, itemizing can be highly beneficial if your eligible expenses exceed the standard deduction amount. Common itemized deductions include:
- State and Local Taxes (SALT): While there’s a cap on the SALT deduction, it can still be a significant factor for taxpayers in high-tax states. Keep track of your property taxes, state income taxes, or sales taxes paid.
- Home Mortgage Interest: If you own a home and pay mortgage interest, this can be a substantial deduction. The limits for deducting mortgage interest generally depend on when you took out your loan and its amount.
- Medical and Dental Expenses: You can deduct the amount of medical and dental expenses that exceed 7.5% of your adjusted gross income (AGI). This includes everything from doctor visits and prescription medications to health insurance premiums and certain long-term care costs. Thorough record-keeping here is key.
- Charitable Contributions: Donations to qualified charitable organizations can be deducted. For 2026, be aware of any potential changes to the limits on cash contributions or other forms of giving. Always obtain proper documentation for your donations.
To make the best choice, meticulously track all potential itemized deductions throughout the year. At tax time, compare the total of your itemized deductions to the standard deduction amount for your filing status. The higher figure is usually the one you should take to maximize your savings.
Beyond the Basics: Overlooked Deductions to Consider
Many taxpayers miss out on valuable deductions simply because they are unaware of them or don’t keep adequate records. Here are a few often-overlooked areas to explore for your 2026 tax deductions:
- Educator Expenses: If you’re a teacher, instructor, counselor, principal, or aide, you might be able to deduct up to a certain amount for unreimbursed expenses for books, supplies, other classroom materials, and professional development courses.
- Student Loan Interest Deduction: You can deduct the amount of interest paid on qualified student loans, up to a certain limit, even if you don’t itemize. This is an above-the-line deduction, meaning it reduces your AGI directly.
- Health Savings Account (HSA) Contributions: Contributions to an HSA are tax-deductible, and withdrawals for qualified medical expenses are tax-free. HSAs offer a triple tax advantage, making them a powerful tool for both healthcare savings and tax reduction.
- Self-Employment Tax Deduction: If you’re self-employed, you can deduct one-half of your self-employment taxes (Social Security and Medicare taxes) from your gross income. This is a significant benefit for independent contractors and small business owners.
- Alimony Payments: For divorce or separation agreements executed before January 1, 2019, alimony payments are generally deductible by the payer and taxable to the recipient. For agreements executed after this date, alimony is neither deductible nor taxable. Confirm the terms of your agreement.
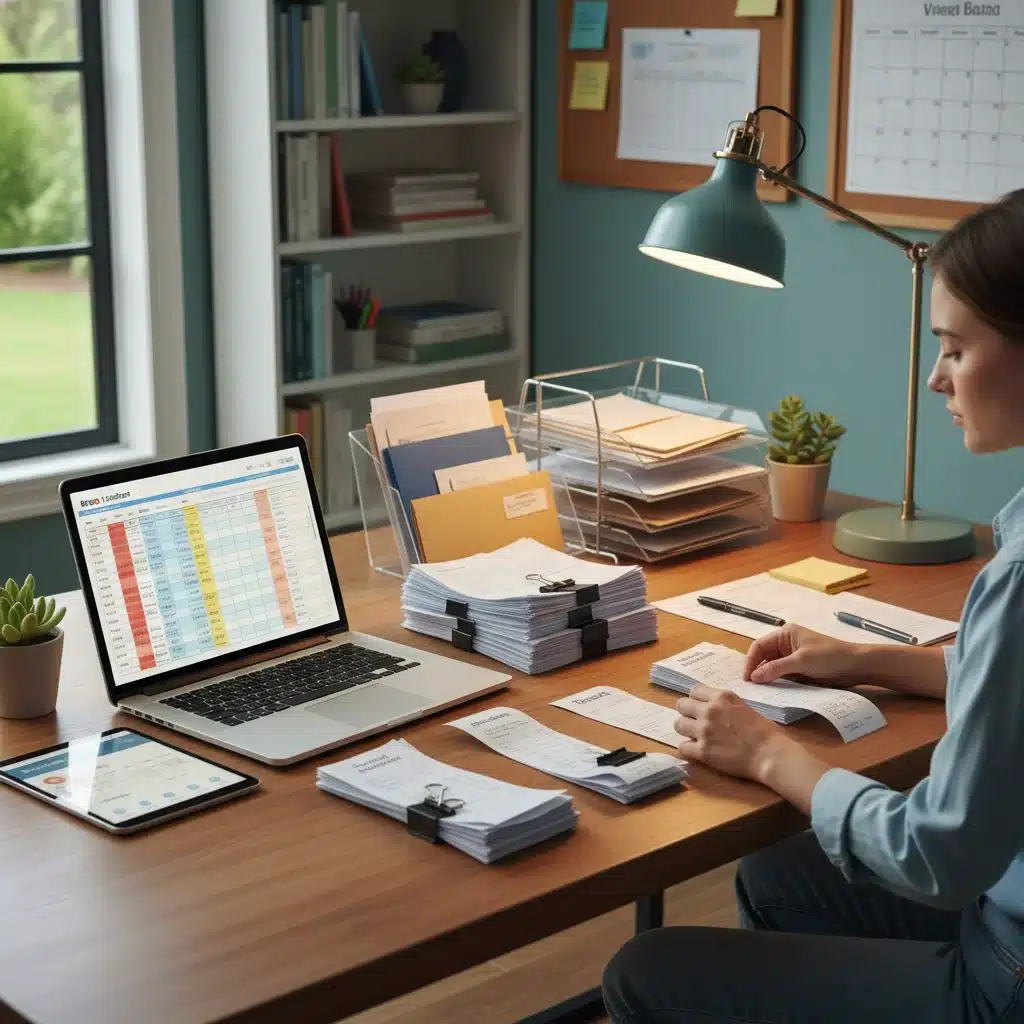
The key to claiming these deductions is meticulous record-keeping. Maintain organized files, whether digital or physical, for all receipts, invoices, and statements related to potential deductions. This proactive approach throughout the year will save you immense time and stress when April 15th approaches and will ensure you don’t miss out on any legitimate savings.
Leveraging Tax Credits to Reduce Your Bill in 2026
While deductions reduce your taxable income, tax credits directly reduce the amount of tax you owe, dollar for dollar. This makes them incredibly powerful tools for lowering your tax bill. Understanding the available credits and your eligibility for them is crucial for maximizing your tax savings in 2026.
Common and Potentially Enhanced Credits for Individuals
Several tax credits are frequently available to individual taxpayers, and some may see enhancements or modifications for 2026:
- Child Tax Credit (CTC): As discussed, the CTC is a significant benefit for families with qualifying children. Depending on legislative changes, the maximum credit amount, refundability, and income limitations could be adjusted. Ensure you meet all dependency tests and income requirements to claim this valuable credit.
- Earned Income Tax Credit (EITC): The EITC is a refundable tax credit for low-to moderate-income working individuals and families. The amount of the credit depends on your income, filing status, and number of qualifying children. It’s one of the largest anti-poverty programs and can result in a substantial refund.
- Education Credits: The American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC) help offset the cost of higher education. The AOTC is generally for the first four years of post-secondary education, while the LLC is for undergraduate, graduate, and professional degree courses, or courses taken to acquire job skills. Be aware of the specific eligibility requirements and maximum credit amounts for 2026.
- Child and Dependent Care Credit: If you pay for child care or care for a dependent so you can work or look for work, you may qualify for this credit. The amount of the credit depends on your income and the number of qualifying individuals.
- Premium Tax Credit (PTC): If you purchase health insurance through a Health Insurance Marketplace, you might be eligible for the PTC to help make your premiums more affordable. Eligibility and credit amounts are tied to your household income.
Credits for Homeowners and Energy Efficiency
For homeowners, several credits can help offset costs related to homeownership and improvements, especially those focused on energy efficiency:
- Residential Clean Energy Credit: This credit is for homeowners who install clean energy property, such as solar panels, solar water heaters, wind turbines, and geothermal heat pumps. The credit amount is a percentage of the cost of new, qualified clean energy property for your home.
- Energy Efficient Home Improvement Credit: This credit is for certain energy-efficient improvements made to your home, such as installing energy-efficient windows, doors, insulation, or certain heating and cooling systems. The maximum credit amounts and eligible improvements are subject to annual adjustments.
These credits not only promote environmental responsibility but also provide a direct financial incentive, reinforcing the importance of considering tax implications in your home improvement projects.
Other Notable Credits to Explore
- Retirement Savings Contributions Credit (Saver’s Credit): This credit is for low- to moderate-income taxpayers who contribute to an IRA or employer-sponsored retirement plan. It’s designed to encourage retirement savings and can be claimed in addition to any deduction for your contributions.
- Foreign Tax Credit: If you’ve paid income taxes to a foreign country, you might be able to claim a credit for those taxes, preventing double taxation.
To claim credits effectively, it’s crucial to understand the eligibility criteria for each. Many credits have income limitations, specific expense requirements, and documentation needs. Don’t assume you don’t qualify; a quick review could uncover significant savings. Just like with deductions, meticulous record-keeping for all expenses related to potential credits is non-negotiable.
Proactive Strategies for Optimal Tax Preparation by April 15th
Waiting until the last minute to prepare your taxes is a recipe for stress and potentially missed opportunities. A proactive approach to tax planning throughout the year can make the process smoother, more accurate, and ultimately, more financially rewarding. Here are some key strategies to ensure you’re fully prepared for April 15th and maximize your 2026 tax deductions and credits.
Year-Round Record Keeping: Your Best Friend
The foundation of successful tax preparation is impeccable record-keeping. Don’t wait until January to start gathering documents. Implement a system early in the year:
- Digital vs. Physical: Choose a method that works for you. Digital records (scanned receipts, cloud storage) offer easy access and backup. Physical files should be organized and stored securely.
- Categorize Expenses: As you incur expenses, categorize them into potential deduction areas (e.g., medical, charitable, business). This makes compilation much faster.
- Track Income: Keep track of all income sources, including W-2s, 1099s, investment income, and any other earnings.
- Bank and Credit Card Statements: Regularly review these statements to identify deductible expenses and ensure accuracy.
Consistent record-keeping not only helps you identify all eligible deductions and credits but also provides the necessary documentation in case of an IRS inquiry.
Mid-Year Tax Review and Adjustments
Don’t let tax season be a surprise. Consider conducting a mid-year tax review, ideally around July or August. This allows you to:
- Project Income and Expenses: Estimate your full-year income and major expenses.
- Adjust Withholding: If your financial situation has changed significantly (e.g., marriage, new job, new baby, significant income increase/decrease), adjust your W-4 with your employer to ensure the correct amount of tax is withheld. This prevents underpayment penalties or a surprisingly large tax bill.
- Plan Major Purchases: If you’re considering a large purchase that might qualify for a credit (like energy-efficient home improvements), a mid-year review can help you time it strategically.
- Optimize Retirement Contributions: Review your contributions to IRAs, 401(k)s, and HSAs. Increasing contributions can reduce your taxable income and boost your savings.
Understanding Estimated Taxes for Self-Employed Individuals
If you’re self-employed, a freelancer, or have significant income not subject to withholding, you are likely required to pay estimated taxes quarterly. Failing to do so can result in penalties. For 2026, ensure you:
- Calculate Your Tax Liability: Use your projected income and deductions to estimate your annual tax liability.
- Pay on Time: Make timely quarterly payments (typically April 15, June 15, September 15, and January 15 of the following year).
- Adjust as Needed: If your income or expenses change throughout the year, adjust your estimated tax payments accordingly to avoid underpayment.
Seeking Professional Guidance
While this guide provides a comprehensive overview, tax laws can be complex, and individual situations vary greatly. For intricate financial scenarios, significant life changes, or if you simply want peace of mind, consulting a qualified tax professional is highly recommended. A tax advisor can:
- Provide Personalized Advice: Tailor strategies to your unique financial situation.
- Identify Overlooked Savings: Uncover deductions and credits you might miss.
- Ensure Compliance: Help you navigate complex regulations and avoid errors.
- Represent You: Assist in case of an IRS audit or inquiry.
The fee for professional tax help is often well worth the potential savings and reduced stress, especially when aiming to maximize your 2026 tax deductions and credits.
Conclusion: Empowering Your 2026 Tax Season Success
The 2026 tax code changes, while presenting new challenges, also offer numerous opportunities for savvy taxpayers to optimize their financial outcomes. By staying informed about inflation adjustments, legislative modifications, and the nuanced differences between standard and itemized deductions, you are already on the path to success. The power to maximize your 2026 tax deductions and credits lies in proactive planning, diligent record-keeping, and a willingness to understand the intricacies of the tax system.
Remember, April 15th is not just a deadline; it’s the culmination of a year’s worth of financial decisions and strategic preparations. By implementing the strategies outlined in this guide—from meticulously tracking your expenses and income to conducting mid-year tax reviews and leveraging available credits—you can approach tax season with confidence. Don’s let the complexity intimidate you; instead, view it as an opportunity to take control of your financial future.
Whether you choose to tackle your taxes independently or seek the expertise of a tax professional, the goal remains the same: to ensure you pay only what you owe and take advantage of every legitimate opportunity to reduce your tax liability. Start preparing today, and make your 2026 tax season a testament to smart financial planning and maximized savings.